Current NFIP dwelling-form exclusion and FloodSmart guidance checked October 4, 2026
Explicit NFIP dwelling-form exclusion plus an original claim-preparation record. Private policies, cause of loss and actual coverage require separate insurer review.
Sources and scope checked .
NFIP flood insurance does not cover fences: its dwelling policy expressly excludes them. That is a clear answer about the National Flood Insurance Program, not a ruling on every private flood policy or homeowners claim. Start by identifying the policy and the cause of loss before deciding how to document a damaged fence. NFIP Dwelling Form, Article IV.12; FloodSmart coverage guidance.
A fence can be damaged during a flood event by different mechanisms, and the word "storm" does not settle an insurance claim. This reference explains the documented NFIP exclusion and provides questions to take to an insurer or licensed agent. It does not determine your coverage, interpret a private contract for you or replace required claim forms.
Where the NFIP fence exclusion appears
The NFIP Standard Flood Insurance Policy Dwelling Form expressly lists fences as property not insured in Article IV, item 12; FloodSmart's public coverage guidance also excludes fences. NFIP Standard Flood Insurance Policy: Dwelling Form. FloodSmart: buying flood insurance and coverage exclusions.
| Source | Location | What it establishes |
|---|---|---|
| Standard Flood Insurance Policy, Dwelling Form | Article IV, Property Not Insured, item 12 | Fences are expressly listed as not insured |
| FloodSmart public guidance | What doesn't flood insurance cover? | Outside-property examples include fences |
| Your actual policy and endorsements | Obtain from insurer/agent | Needed to identify the policy and any separate coverage question |
We checked the current eCFR dwelling-form text on October 4, 2026; eCFR displayed Title 44 current through October 1, 2026. Its form amendment citations are through 2021. The fence exclusion also appears in FEMA's October 2021 F-122 dwelling form, but our finding links the current eCFR text and the current public FloodSmart guidance rather than presenting a review date as a new policy edition.
The NFIP insures defined buildings and eligible contents subject to its policy; the existence of building coverage is not evidence that every outdoor improvement is included. A specific fence exclusion should not be replaced with an assumption that the fence is covered because it is attached, expensive or needed for security. Ask the insurer for a written explanation tied to the applicable provision.
NFIP, private flood and other storm damage
A fence's NFIP exclusion does not establish that all private flood policies exclude fences; this reference does not determine private-policy coverage. NFIP Standard Flood Insurance Policy: Dwelling Form.
FloodSmart says most homeowners and renters insurance policies do not cover flood damage; a storm-damaged fence still needs a cause-of-loss and actual-policy review rather than an assumption based on the storm's name. FloodSmart: buying flood insurance and coverage exclusions.
| Situation | Starting point | Do not assume |
|---|---|---|
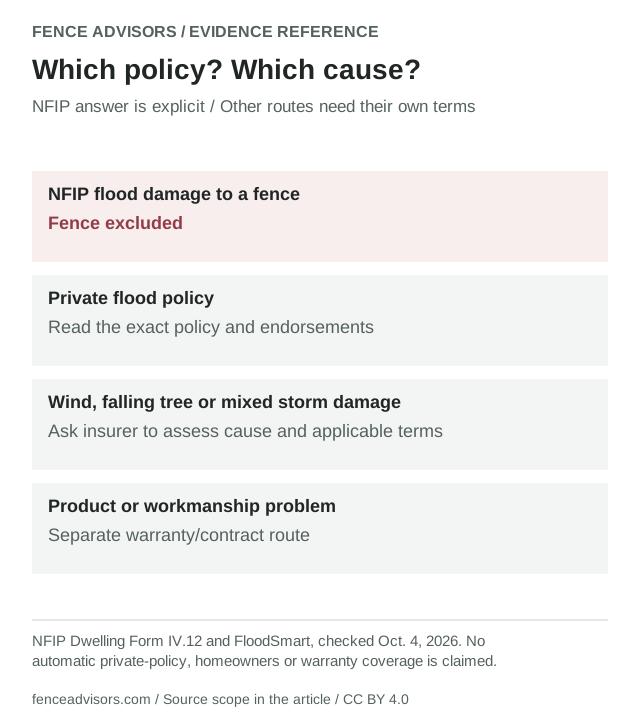
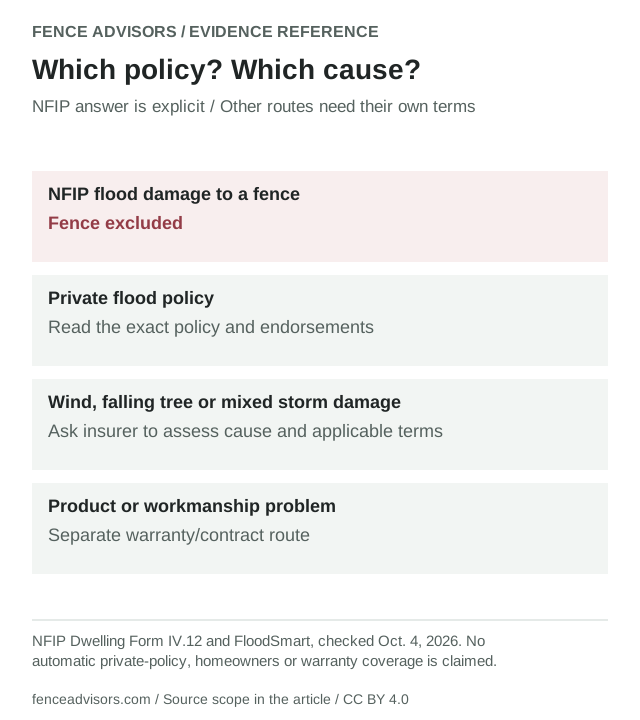
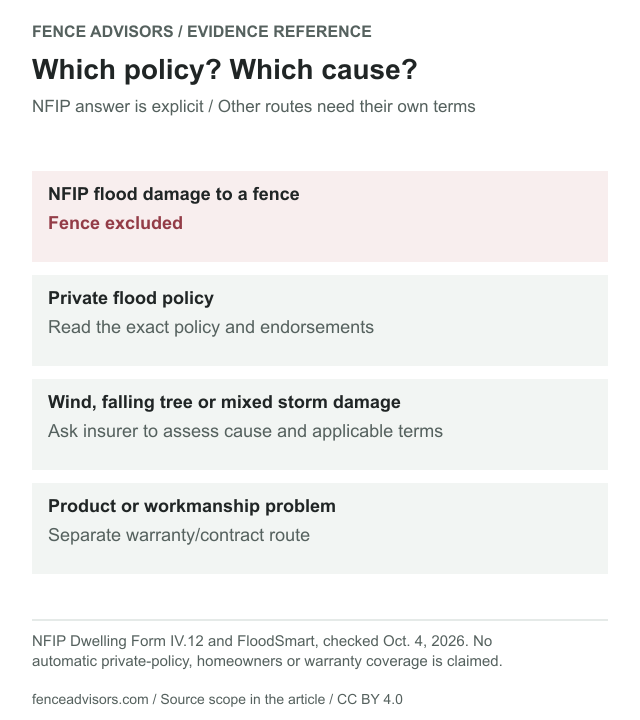
| NFIP flood damage to a fence | Fence excluded | Dwelling Form Article IV.12; FloodSmart public guidance |
| Private flood policy | Read the exact policy and endorsements | Not determined by this NFIP reference |
| Wind, falling tree or mixed storm damage | Ask insurer to assess cause and applicable terms | Storm name alone does not decide coverage |
| Product or workmanship problem | Separate warranty/contract route | Warranty and insurance are not interchangeable |
The first row is the sourced NFIP fence exclusion. The remaining rows are questions and boundaries, not researched guarantees of private-policy, wind or warranty coverage. If a tree, moving water, wind and debris all affected the site, describe what you observed rather than assign a legal cause yourself. Let the insurer assess the evidence and applicable terms.
Ask specifically whether any proposed payment concerns the fence, another insured item or a separate expense. Approval of one part of a storm claim is not automatic approval of the fence replacement. Deductibles, limits, depreciation, exclusions and proof requirements also need the actual policy; there is no universal fence reimbursement figure in this reference.
Download or embed this graphic
<figure>
  <a href="https://fenceadvisors.com/blog/does-flood-insurance-cover-fences"><img src="https://fenceadvisors.com/media/research/fence-flood-coverage-boundaries.svg" alt="NFIP Dwelling Form Article IV.12 excludes fences. Private flood terms and non-flood storm damage require separate policy and cause-of-loss review. Product or workmanship problems use a separate warranty or contract route." width="640" height="720" loading="lazy" style="max-width:100%;height:auto"></a>
  <figcaption>Graphic: <a href="https://fenceadvisors.com/blog/does-flood-insurance-cover-fences">Fence Advisors</a>. Source, period and limitations are in the linked article. Original graphic: CC BY 4.0.</figcaption>
</figure>
Prepare a safe fence-loss record
The Fence Advisors fence-loss record is a blank preparation worksheet, not an insurance claim form, proof of coverage or an instruction to remove damaged property before documenting it safely.
Safety comes before documentation. Stay away from unstable panels, electrical hazards, contaminated water and unsafe gate systems. Do not enter a dangerous area to take a photo. Obtain appropriate professional help for immediate hazards; ask your insurer for documentation and authorization instructions as soon as practical.
| Record | Useful detail |
|---|---|
| Event and observations | Date, location and factual description of damage, without guessing coverage |
| Fence identity | Materials, approximate affected runs, gates and known pre-loss condition |
| Safe evidence | Overall and detail photos when safe; existing earlier photos if available |
| Policy | Insurer, policy type, applicable form and endorsements |
| Insurer response | Case number, named contact, provision cited and written next step |
| Required procedure | Actual forms, supplied deadlines, permission and requested evidence |
| Repair scope | Separate repair, replacement, removal, gate, access and disposal items |
| Costs and actions | Itemized proposals, authorized emergency work and receipts |
The CSV stays blank so you can record actual facts. A blank field means unknown, not covered or included. Keep policy numbers, addresses and receipts private; do not post claim files publicly. Use the insurer's supplied deadlines and current instructions rather than assume one generic deadline applies to every disaster or policy.
An itemized scope helps even if the fence is not covered. Compare retaining sound components with the replacement proposal, and clarify required access or removal. Our storm-damage repair guide covers the repair discussion; the quote checklist helps normalize scope. Find local fence contractors for a safe assessment, not an insurance determination.
Keep insurance, repair contracts and warranties separate
A product defect, installation issue and flood loss are not the same event. A manufacturer warranty is governed by its own terms and may have exclusions; do not assume that a warranty will pay because flood insurance does not. Use our warranty claim checklist to identify the exact product, purchase and applicable document before opening that separate route.
If the repair scope changes after work begins, document additions, credits and schedule consequences with the change-order record. Insurer communication does not by itself authorize every change to your contractor's agreement. Keep the insurer's process and the signed project scope as separate records.
The NFIP fence exclusion is also not a reason to dismiss flood coverage for the home and eligible contents. Their risks and coverage questions are different. Discuss the actual property and policy needs with a licensed agent rather than make a purchase decision from one excluded outdoor item.
Methodology and reuse
We reviewed the fence exclusion in the current eCFR NFIP dwelling form and FloodSmart's public coverage guidance. The FEMA October 2021 dwelling-form PDF was also retrieved in full, with its exclusion/definition passages inspected. We did not analyze a specific claim, survey private policies or verify coverage for wind, debris or emergency repairs. The original graphic is a question map; the downloadable record is not a proof-of-loss form. A citation should name NFIP, the dwelling form and IV.12, not turn the finding into "all flood insurance excludes fences."
Frequently Asked Questions
Does NFIP flood insurance pay to replace a fence?
The NFIP Dwelling Form expressly lists fences as property not insured in Article IV.12. FloodSmart's public guidance confirms the exclusion.
Could a private flood policy have different terms?
This NFIP reference does not determine private-policy coverage. Read the exact policy and endorsements and ask the insurer or licensed agent for a written answer.
Is a fence covered if it was damaged during a hurricane?
The event name alone does not determine coverage. The cause of loss and the actual policy matter; this article does not decide wind, flood or mixed-damage claims.
Sources and Downloads
- Blank fence-loss evidence and insurer-question recordCSV
- Citable findings, exact sources and evidence boundariesCSV
- Source dates, review scope and original modelsJSON
- NFIP Standard Flood Insurance Policy: Dwelling Form
- FloodSmart: buying flood insurance and coverage exclusions
Original Fence Advisors graphics, data compilations and worksheet are available under CC BY 4.0. Retain source, period and scope when reusing data. This license does not relicense third-party documents or trademarks.
Corrections: editorial@fenceadvisors.com.
Related Research
Put your research to work
Estimate your budget, then compare fence companies in your area.
Get the next guide in your inbox
Fence costs, rankings, and what AI is telling homeowners — researched, no fluff.